Positive Momentum from Europe, Major Individual Markets Falter
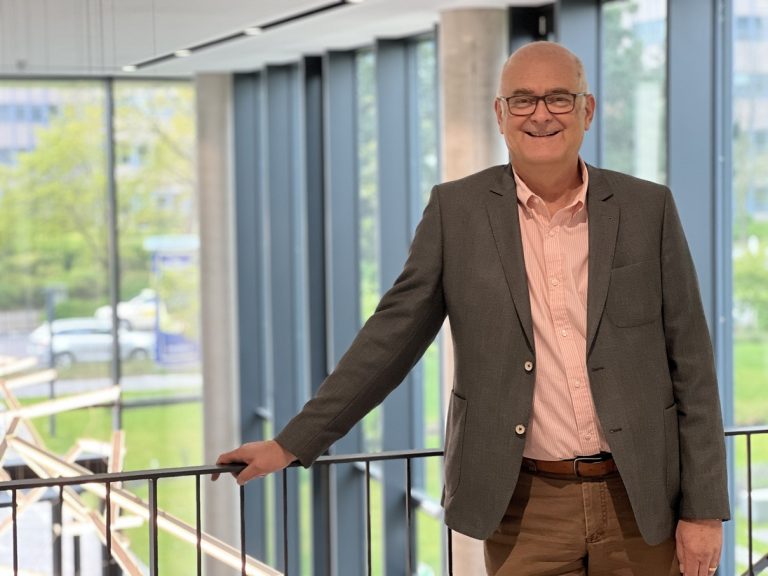
Richard Clemens, spokesperson for the VDMA Process Technology Forum (Image source: VDMA e.V.)
“Europe is an important market for environmental technologies from Germany,” summarizes Richard Clemens, spokesperson for the VDMA Process Technology Forum. “At the leading international trade fair IFAT Munich, exhibitors and visitors can experience the industry’s innovative strength firsthand.”
Waste Treatment and Recycling Technology: An Optimistic Outlook
Following a mixed year in 2025, the economy in the waste treatment and recycling Technology sector is stabilizing. The latest economic survey by the VDMA Waste and Recycling Technology association shows that order intake is developing very positively in 2026, and industry revenue is also on the rise again.
According to the survey, manufacturers expect nominal revenue growth of 2.3 percent for 2026, following a slight decline of 1.3 percent in 2024. An initial recovery was already evident in 2025, with growth of 1.5 percent. Order intake is currently developing positively, having already increased by 2.2 percent last year following a real decline of 0.8 percent in 2024. For this year, manufacturers are even anticipating order growth of 4.5 percent.
Overall, there is a noticeable shift in demand toward the European market. Forecasts indicate that in 2026, approximately 60 percent of exports of waste treatment and recycling technology will go to EU countries, significantly more than in the previous year. At the same time, key sales markets outside the EU are losing importance. According to the manufacturers surveyed, the export share of non-EU countries will drop to 7.8 percent, North America to 9.0 percent, while the Middle East, at 4.2 percent, and China, at just 0.6 percent, will fall significantly behind.
The industry is benefiting above all from EU-wide investments in the circular economy, stricter environmental regulations, and political support programs, from which companies also expect positive momentum in the coming years.
Air Handling Technology: Subdued Momentum, Impacts from Other European Countries
The overall picture for air handling technology is mixed. In 2025, real order intake remained 5 percent below the previous year’s level. While domestic business declined significantly (down 14 percent), foreign order intake stabilized with a 5 percent increase. A noticeable upturn emerged at the start of 2026: In the first two months, total order intake was 13 percent higher than in the same period the previous year, driven by foreign markets (up 24 percent). This development underscores the high importance of international markets against the backdrop of a domestic economy that remains subdued.
Foreign trade once again proved to be an important anchor of stability in 2025. Exports of air handling technology from Germany reached a volume of 14.5 billion euros, slightly exceeding the previous year’s figure (up 1 percent). There were regional differences: While exports to the U.S., the largest single market, declined moderately by 5 percent, China recorded a significantly sharper decline (down 14 percent). The EU internal market maintained its central role with a 2 percent increase and accounted for more than half of total exports.
This close European integration is also reflected on the import side. In 2025, the value of imports amounted to around 11.6 billion euros, of which approximately 7.9 billion euros originated from the EU-27. The figures illustrate the high degree of interdependence based on the division of labor within Europe, as well as the complementary importance of selected nonEuropean partners within international value chains.
Overall, the companies’ international positioning contributes to the sector’s resilience. The slight increase in export figures at the beginning of 2026 suggests that foreign business could provide additional momentum as the year progresses, provided that the international environment remains stable and demand in the European market gradually strengthens.
Industrial Valves: Headwinds at the Start of the Year
Following a strong 2025, the industrial valve sector has started the current year on a much more subdued note. Although revenue in 2025 was up 7 percent (up 4 percent after adjusting for price changes), clearly exceeding expectations – with domestic business growing by 4 percent and international revenue rising by as much as 9 percent – However, this momentum stalled at the beginning of 2026. Clear signs of a slowdown were already evident before the outbreak of the conflict in the Middle East. Sales fell by a total of 8 percent from January to February, and by as much as 10 percent on a price-adjusted basis. Domestic sales fell by 9 percent, while international sales dropped by 7 percent. While the eurozone managed a slight increase of 1 percent, sales in non-eurozone countries fell by 10 percent.
The export sector also saw shifts at the start of the year: for the first time in many years, China has slipped to second place among the most important customer countries. The U.S. has taken the top spot. Shipments to the United States grew by 5 percent through the end of February. Exports to the EU also rose by 5 percent. Europe is by far the most important customer region. Around 48 percent of exports are destined for the European single market.
A short-term improvement in the situation is currently not in sight. High energy and raw material prices, as well as constraints on intermediate goods, are now meeting with noticeable investment reluctance in many sales markets. Added to this are location factors in Germany and Europe that still leave room for improvement. Against this backdrop, the VDMA Valves association expects a slight decline in sales for industrial valves and fittings this year. In the longer term, however, the outlook is positive. The industry is robustly positioned and has proven to be very resilient even in past crises.
Liquid Pumps: Slight Increase in 2025
Exports of liquid pumps (excluding hydraulic pumps) increased by 1.7 percent in 2025 compared to the previous year, reaching EUR 6.3 billion. In the first two months of the current year, exports rose by 0.5 percent year on year to EUR 1 billion. The most important destination market was the EU-27, accounting for 47 percent. The leading customer countries were the United States (EUR 648 million), followed by China (EUR 521 million) and France (EUR 387 million).
Imports increased by 2.6 percent in 2025 compared to the previous year, reaching EUR 3.2 billion. The main countries of origin were China (EUR 378 million), Italy (EUR 356 million), and the United States (EUR 310 million).
Real order intake in 2025 was 2 percent higher than in the previous year. In the first two months of the current year, a year-on-year decline of 8 percent was recorded.
At the beginning of 2026, 60 percent and 50 percent respectively of pump manufacturers surveyed in the VDMA-wide economic survey rated the situation in the key customer sectors water and wastewater as good to very good. Companies are also confident about business prospects in these areas: one third and 9 percent respectively expect business to improve or improve significantly.
Compressors, Compressed Air and Vacuum Technology: Order Growth at the Start of 2026
Exports of compressors, compressed air and vacuum technology declined by 5.3 percent in 2025 year on year to EUR 5.9 billion. In the first two months of the current year, exports fell by 8 percent compared to the same period as the previous year, to EUR 915 million. The EU-27 was the most important destination market, accounting for 49 percent. The leading customer countries were the United States (EUR 625 million), China (EUR 601 million), and Italy (EUR 323 million).
Imports rose by 6.3 percent in 2025 to EUR 3.2 billion. The main countries of origin were China (EUR 340 million), Italy (EUR 281 million), and Poland (EUR 269 million).Real order intake in 2025 was 16 percent below the previous year’s level, while in the first two months of the current year it increased by 15 percent year on year.
Process Plant and Equipment from Germany: Local Conditions Weigh on the Industry
In 2025, the Process Plant and Equipment sector recorded exports totaling approximately 6.3 billion euros – an increase of 3.6 percent over the previous year. Growth momentum came primarily from business with EU partner countries, while exports to the two most important individual markets, the U.S. and China, declined. The weak performance of the domestic market remains a cause for concern.
In the first two months, the sector recorded an overall decline in exports of 4.7 percent. Growth was concentrated primarily in Europe, East Asia, and South America. Business with European countries outside the EU-27 developed particularly dynamically, with German exports rising by 18.4 percent.
The trends in the two largest individual markets diverged significantly: While exports to the U.S. plummeted by 32.2 percent, China recorded a strong increase of 37 percent.
Developments in order intake are disappointing. Adjusted for price changes, domestic business in 2025 declined by 11 percent compared to the previous year, while foreign orders fell by 33 percent.
Still, the start of 2026 was better than the previous year, though this does not yet indicate a decisive turnaround: Domestic orders in February 2026 were 7 percent higher in real terms than the comparable figure for 2025, while foreign orders rose by 42 percent. Growth was particularly strong among eurozone partner countries, with an increase of 47 percent, while orders from non-eurozone countries rose by 40 percent. Business conditions remain problematic: High production costs and rising energy prices are weighing on companies and reducing sales.
Exports of water and wastewater technology, a sub-sector of process plant and equipment, rose by 5.6 percent to 1.37 billion euros in 2025. Exports performed rather weakly in the first two months of 2026 (down 5.3 percent). The U.S. market – the industry’s second-largest sales market –performed weakly, with a significant decline in exports of 17.9 percent.
IFAT Munich 2026: Spotlight Textile recycling
Close to the action with relevant topics: In 2026, the VDMA will once again accompany the leading trade fair for environmental technologies, IFAT Munich, with the Spotlight Area “Circular Textile Handling – Towards a Better Future”, as well as with the VDMA Praxistage and the impressive VDMA Crushing Zone.
The programme is highly diverse, ranging from textile recycling and wastewater treatment to battery and plastics recycling. For every challenge, providers of environmental technologies offer efficient solutions.
In the Spotlight Area, VDMA, together with Lindner Recyclingtech GmbH, EREMA Engineering Recycling Maschinen und Anlagen and Fraunhofer UMSICHT, will demonstrate how end-of-life textiles can be transformed into a valuable resource. Visitors will gain insights into the process landscape of textile recycling – from pre-treatment and washing to sorting, as well as the various pathways of recycling and reprocessing.
Source: VDMA e. V.